For more than three decades, I've watched the merchant acquiring industry reinvent itself, resist change, embrace change, and occasionally contradict itself so spectacularly that you have to wonder whether anyone remembers what they were saying five years ago.
The latest example?
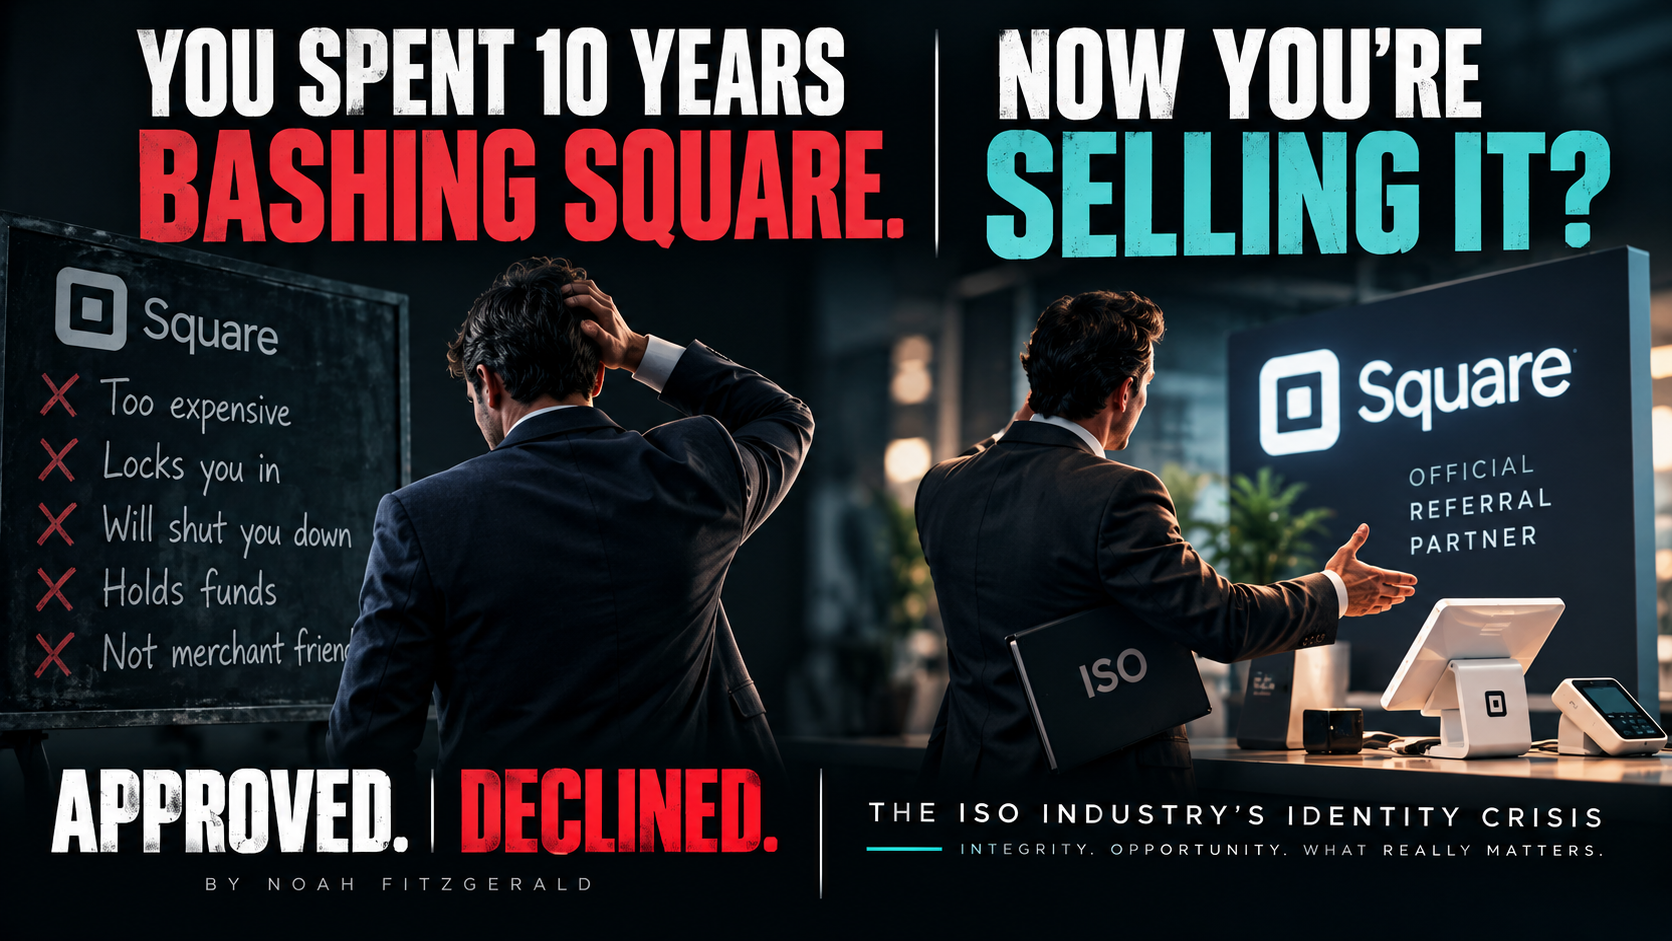
Traditional ISOs promoting Square.
Yes. Square.
The same company that so many independent sales organizations and agents spent years warning merchants about.
Too expensive.
Risk of funding holds.
Account shutdowns.
Limited flexibility.
A closed ecosystem.
I've heard these objections repeatedly throughout the industry. In some situations, they were legitimate concerns. In others, they were sales tactics designed to position traditional merchant accounts as the superior alternative.
But now I'm seeing some of those same organizations promote Square as a solution.
And I can't help asking:
What changed? The technology? The economics? Or the commission?
1. The Convenient Evolution of an Industry Opinion
Let me be clear about something.
Changing your opinion isn't hypocrisy.
In fact, one of my fundamental business principles is being adaptive. Markets evolve, technology improves, and successful operators must be willing to reconsider their assumptions.
Square today isn't the Square of 2015.
Its capabilities have expanded significantly beyond simple card acceptance into a comprehensive commerce ecosystem.
It has become a formidable technology company, serving businesses across retail, hospitality, services, and other industries.
And it deserves recognition for that achievement.
But here's where I draw the line.
If you spent years telling merchants that Square was fundamentally the wrong choice, and now you're recommending it because there's a referral payment available, you owe those merchants an explanation.
What changed in your analysis?
What changed in the merchant's needs?
What changed in the underlying economics?
Or did the only thing that change happen to be your compensation?
Integrity isn't about never changing your mind. It's about being transparent about why you changed it.
2. Square May Be Playing Chess While ISOs Are Playing Checkers
Let's examine what's actually happening.
Square has established a formal referral partner program that rewards organizations for bringing new merchants into its ecosystem.
According to Square's published program, new partners can earn at least $1,000 for qualifying referrals that process $250,000 or more annually, subject to contractual terms.
That's not speculation. That's Square's own published offer.
Now consider what Square receives in return.
Another merchant.
Another business operating on its software.
Another relationship inside its ecosystem.
Another opportunity to provide payments, financial services, software, hardware, and additional capabilities.
And potentially years of ongoing commercial value.
What does the referring ISO receive?
Compensation defined by its referral agreement.
Maybe that's attractive. Maybe it isn't.
But it raises an important question.
Are you being compensated for the lifetime value you're helping create—or simply for delivering the customer?
I don't criticize Square for this.
It's a smart distribution strategy.
Why build every sales relationship directly when you can incentivize an established industry of independent sales professionals to introduce merchants to your platform?
Square is leveraging a distribution network that spent years competing against it.
That's remarkable.
And from a strategic perspective, potentially brilliant.
3. The Real Cost Isn't the Commission. It's the Opportunity You Surrender.
Traditional ISOs have historically built enterprise value around several critical assets:
- Merchant relationships and distribution.
- Recurring processing residuals.
- Contractual rights and portfolio economics.
- Opportunities to cross-sell additional products and services.
- Long-term retention and predictable cash flow.
These assets form the foundation of many ISO business valuations.
Now consider what happens when an ISO introduces a merchant directly into another company's vertically integrated ecosystem.
Who controls the payment-processing relationship?
Who controls the core software experience?
Who determines the product roadmap?
Who controls pricing, onboarding, and the availability of additional financial services?
And perhaps most importantly:
Who has the strongest position to sell that merchant the next product?
The answers depend on the specific agreement, but in a standard referral arrangement, the referring ISO should not assume it retains the same rights it would have under its own merchant acquiring relationship.
This is where the economics become interesting.
A referral payment may look attractive today.
But what is the long-term cost of directing a merchant into a platform where your role may become secondary?
What happens when that merchant needs lending, payroll, loyalty, marketing, or additional locations?
Will they call you?
Or will they use the tools already integrated into their Square dashboard?
That's not a criticism of Square.
That's the competitive advantage of an integrated platform.
And it's precisely why ISOs should think carefully before becoming another distribution channel for one.
4. Does Square's Referral Program Prove Merchants Were Overpaying?
I've heard this argument, and I understand the logic.
If Square can now compensate third parties to acquire merchants, doesn't that suggest its pricing has always included substantial margin?
Possibly.
But the existence of a referral program alone doesn't prove overcharging.
Customer acquisition has a cost. Every successful platform must decide how much it can afford to spend to acquire a customer relative to that customer's expected lifetime value.
Square can potentially recover acquisition costs across processing, software, hardware, lending, and other financial products.
That's the real insight.
Square understands the lifetime economics of a merchant relationship.
And that is exactly what ISOs should be thinking about.
Not just this month's residual.
Not just the next bonus.
Not just the easiest product to close.
The lifetime value of the relationship.
5. What If ISOs Built Their Own Ecosystems Instead?
Here's where I think the industry is missing a much larger opportunity.
For years, traditional ISOs have relied on payment processors, terminal manufacturers, gateways, and software providers to determine what they could sell.
The ISO's primary differentiator was often pricing, service, or the relationship with the merchant.
But technology has changed.
Today, an ISO can explore branded commerce platforms that combine mobile POS, payment acceptance, customer management, scheduling, loyalty, reporting, and business operations.
Instead of referring a merchant into someone else's ecosystem, the ISO can potentially offer a technology experience under its own brand, paired with an acquiring relationship it has negotiated.
Imagine the difference.
A merchant downloads your branded app.
They operate their business using your commerce solution.
Their processing relationship is structured through your acquiring partnership.
You develop recurring software revenue alongside processing revenue.
You become more relevant to the merchant's daily operations.
And instead of competing primarily on rates, you compete on the value of the complete business solution.
That's a different business model.
One that can create a more defensible relationship and potentially a more valuable enterprise.
Of course, these advantages depend on the actual contracts. White-label branding does not automatically mean ownership of the software, merchant data, or processing agreement.
But the opportunity is real.
6. Platforms Like Cutflow Represent an Alternative Direction
One example worth exploring is Cutflow.
Cutflow offers a connected business operating platform combining POS, payments, scheduling, customer management, inventory, analytics, and other operational capabilities.
Its payment infrastructure also promotes embedded payment acceptance and revenue-sharing models for distribution partners.
For ISOs, platforms in this category create an opportunity to rethink what they sell.
Instead of being a merchant account salesperson, become a provider of commerce technology and business infrastructure.
Instead of selling the same commodity processing product as everyone else, build a differentiated solution.
Instead of relying entirely on someone else's distribution strategy, develop your own.
That doesn't mean every ISO should become a software company.
And it certainly doesn't mean every ISO needs to build technology from scratch.
It means evaluating whether partnerships with flexible software providers could give you more control over your customer experience, commercial relationships, and recurring revenue.
Before making that decision, validate processor compatibility, branding rights, customer-data access, revenue ownership, portability, support responsibilities, and exit provisions.
The objective isn't to exchange one dependency for another.
It's to build a business with more strategic options and more durable value.
7. The Cost of Inaction Is Becoming the Real Threat to Traditional ISOs
This is where one of my strongest business beliefs comes into play.
The Cost of Inaction.
For decades, the acquiring industry has been extraordinarily effective at selling the same fundamental service through different pricing models, compensation structures, and distribution channels.
But the merchant's needs have changed.
They don't simply need to accept a credit card.
They need to run a business.
Payments are becoming embedded in software, operational workflows, financial services, and customer experiences.
And the companies controlling those experiences are increasingly positioned to control the economics.
Traditional ISOs have a choice.
They can continue to compete primarily on processing price and commissions.
They can become referral channels for larger technology platforms.
Or they can evolve into businesses that deliver broader operational value.
None of these paths is universally wrong.
But failing to understand the strategic consequences of each is a serious mistake.
The greatest threat to the traditional ISO isn't Square. It's the industry's unwillingness to evolve beyond selling payment processing.
8. Where Is the Integrity?
I want to return to the issue that bothers me most.
Integrity.
I don't believe there is anything inherently wrong with recommending Square.
For many merchants, it may be an excellent choice.
Simple onboarding, recognizable technology, integrated tools, and predictable published pricing can offer meaningful advantages.
And if Square is genuinely the best solution for a merchant, an ISO should be willing to recommend it.
Even if that recommendation generates no commission.
That's what being a trusted advisor means.
But if your recommendations change based primarily on which provider pays you, while the merchant's needs remain unchanged, then we have a problem.
Because at that point, you're not advising the merchant.
You're monetizing the relationship.
And there is a difference.
I have spent more than 30 years in this industry, and I've seen extraordinary professionals who genuinely put their merchants first.
I've also seen how compensation structures can influence recommendations in ways that aren't always aligned with merchant interests.
The industry deserves better than simply following the next incentive program.
It deserves professionals who understand technology, evaluate economics, challenge assumptions, and put the long-term interests of their clients ahead of the next commission.
9. Approved. Declined.
APPROVED: Square's strategy.
Square has built a compelling ecosystem, established a powerful brand, and found another way to expand distribution. That's smart business.
APPROVED: ISOs who adapt.
Changing your opinion because the facts, products, or customer requirements have changed is exactly what good operators should do.
DECLINED: Commission-driven hypocrisy.
If you spent years criticizing a solution and now promote it without explaining what changed, your credibility deserves scrutiny.
DECLINED: Sacrificing long-term enterprise value for short-term convenience.
Building someone else's ecosystem can be a valid business choice. Doing it without understanding the opportunity cost is not.
The Bottom Line
The question isn't whether Square is good or bad.
The question is whether traditional ISOs understand the business they're actually building.
Are you creating an asset with durable customer relationships, recurring economics, differentiated technology, and long-term enterprise value?
Or are you becoming a customer acquisition channel for someone else's platform?
Stop chasing the next commission. Start building the next generation of merchant services.
And if you're going to call yourself a trusted advisor, make sure the advice is worth more than the referral fee.
What's your verdict?
Is becoming a Square referral partner a smart strategic evolution for traditional ISOs—or a dangerous surrender of their future?
I'd especially like to hear from ISO owners, independent agents, processors, software providers, and anyone who has evaluated the long-term economics of these partnerships.
Noah Fitzgerald, CPP — 30+ years in payments, fintech, and building businesses.
Never Stop Building. Never Stop Becoming.